FCA Opens Consultation on Tokenized Gold
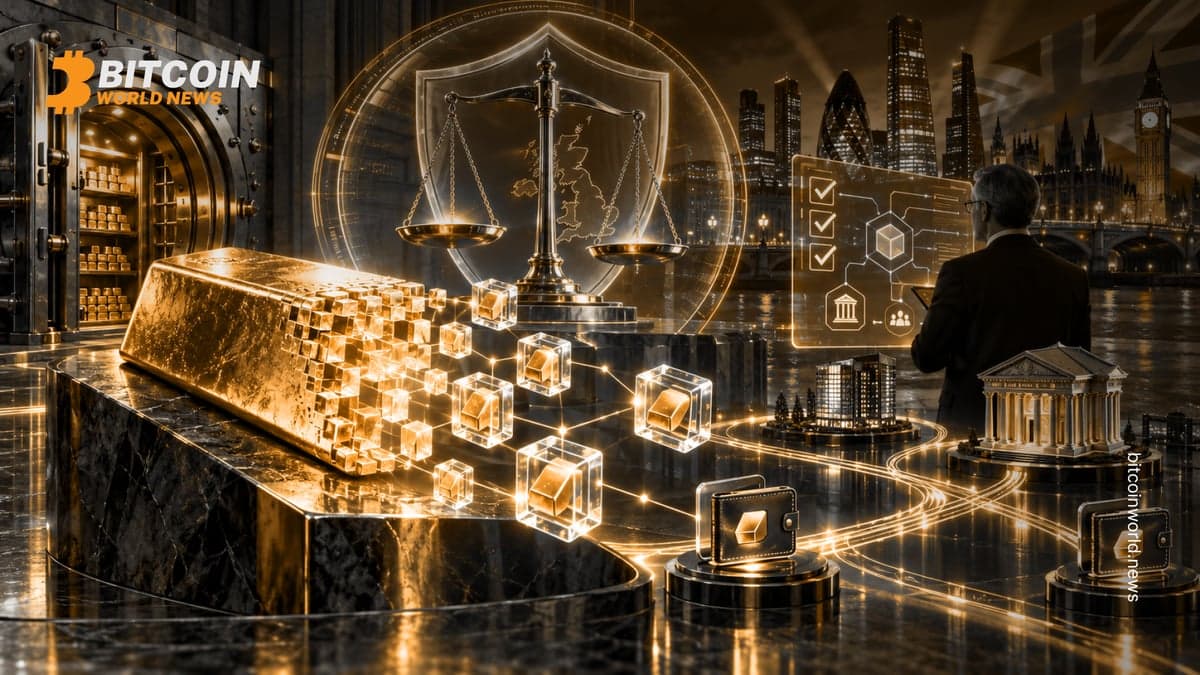
The UK Financial Conduct Authority (FCA) is taking a closer look at how tokenized gold should be regulated, opening the possibility of a dedicated framework for the growing digital-asset market.
The regulator published its Call for Input: Tokenised gold – opportunities and risk for UK wholesale markets on September 14, 2026. The consultation asks market participants whether putting physical gold on distributed ledgers could make the asset easier to trade, transfer, pledge and hold across UK markets. The FCA is accepting responses until October 23, 2026.
The FCA says the feedback could ultimately lead to guidance or a bespoke regime for tokenized gold. Importantly, this is not yet a final exemption from existing fund regulations. Instead, the regulator is examining whether current rules, including the boundaries around collective investment schemes (CIS) and alternative investment funds (AIFs), are appropriate for tokenized gold.
FCA Tokenised Gold Call for Input
Why London’s Gold Market Matters
The FCA's interest comes against the backdrop of London's longstanding role in global gold trading.
The World Gold Council estimates that the London over-the-counter gold market accounts for approximately 70% of global notional trading volume. London also hosts the global reference benchmark for gold and benefits from a large network of vaulting and clearing infrastructure.
That position is important to the UK's regulatory strategy. The FCA says respondents to its earlier work on wholesale tokenization specifically raised gold as a use case, prompting the regulator to examine the asset in greater detail. It wants to understand whether tokenization can improve market efficiency and competitiveness while preserving the strengths of London's existing gold infrastructure.
World Gold Council: Global Gold Market
What Tokenized Gold Actually Means
Tokenized gold refers to digital tokens representing ownership of physical gold. Instead of transferring the underlying bullion every time ownership changes, the ownership interest can be represented and transferred electronically through distributed-ledger technology.
The FCA is particularly interested in wholesale applications. According to the regulator, tokenized gold could make the metal easier to use across digital markets, including potentially as wholesale collateral. It could also create opportunities for new forms of retail investment and financial-product innovation.
The concept therefore goes beyond simply creating a digital version of gold for investors. If the regulatory and infrastructure conditions are suitable, tokenized gold could become part of broader financial-market processes involving trading, transfers, collateral and settlement.
Existing Fund Rules Are Under Review
One of the FCA's main questions concerns the regulatory perimeter surrounding tokenized gold.
The regulator specifically wants feedback on whether uncertainty around the collective investment scheme (CIS) and alternative investment fund (AIF) rules creates challenges for firms developing tokenized-gold products. It is seeking views from gold-market participants, clearing members, asset managers, technology providers, firms developing tokenized-gold products and investors.
The FCA has not committed to removing tokenized gold from those rules. Instead, it says the responses will help determine its future approach, which could include guidance or a dedicated regulatory regime. This distinction is important because the current announcement is a consultation, rather than a completed regulatory change.
Tokenized Gold Fits Into a Wider UK Strategy
The new consultation follows broader efforts by UK regulators to establish infrastructure and rules for tokenized financial markets.
In May, the FCA and Bank of England published a joint call for input on the future of tokenization in UK wholesale markets. The authorities said tokenization could significantly change wholesale financial markets and sought industry views on how to support its safe adoption.
The FCA and Bank of England have also been examining the use of tokenized assets as collateral. Their joint work identified tokenized gold and tokenized money-market funds as potential forms of uncleared over-the-counter collateral, subject to appropriate standards and risk controls.
FCA and Bank of England: Tokenisation in Wholesale Markets
This broader programme is designed to give financial firms more clarity around tokenized securities, collateral and settlement while maintaining market integrity and appropriate safeguards.
UK and US Also Push Tokenization Cooperation
The UK's tokenization strategy extends beyond domestic regulation.
In July, the UK and US published recommendations from the Transatlantic Taskforce for Markets of the Future, focusing on closer cooperation in digital assets and capital markets. The initiative aims to reduce fragmentation, improve cross-border connectivity and accelerate adoption of tokenization across financial markets.
The two governments described digital assets and distributed-ledger technology as increasingly important to financial markets and said their recommendations were intended to strengthen connections between the world's two leading financial centres.
UK-US Transatlantic Taskforce Recommendations
FCA Wants Industry Feedback Before Acting
The FCA's September 14 consultation makes clear that the regulator is still gathering evidence before deciding how tokenized gold should fit into the UK's regulatory framework.
The consultation closes on October 23, 2026, after which the FCA will review responses and use them to shape its future approach. Possible outcomes include additional guidance or the creation of a bespoke regime specifically for tokenized gold.
That approach reflects the UK's broader attempt to encourage financial-market innovation without abandoning existing safeguards. For London, the stakes extend beyond cryptocurrency: tokenized gold could eventually connect one of the world's largest traditional bullion markets with digital financial infrastructure.
The FCA's latest move therefore represents an early but significant step in determining how physical gold can interact with tokenized markets. Rather than immediately exempting tokenized gold from fund rules, the regulator is now asking the industry whether a different framework is needed — and whether that framework can help London remain competitive as global gold trading becomes increasingly digital.