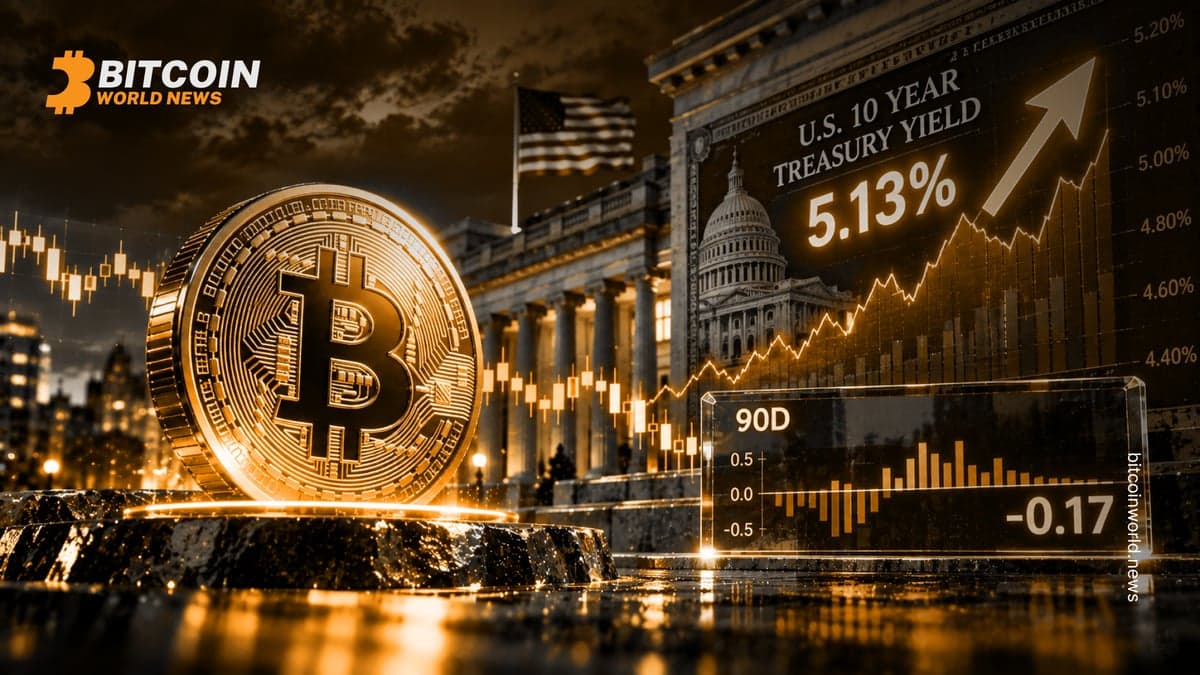
Bitcoin (BTC) held near $83,262.77 on Wednesday while the U.S. 10-year Treasury yield surged 15 basis points to 5.13%, the highest level since 2007. The move revived the view that higher yields raise the opportunity cost of holding non-yielding assets like bitcoin and gold. Yet over most of bitcoin’s history, bond correlations have been weak or inconsistent.
Yields snapped higher across major markets alongside the 10-year benchmark, refocusing attention on macro pressures that typically weigh on risk assets. The standard playbook says investors rotate toward income as coupons climb. The data, however, point to a limited and unstable relationship between bitcoin returns and government bond yields over multi-month horizons.
Why aren’t higher yields dragging Bitcoin lower?
Because bitcoin’s return profile has shown little to no consistent correlation with bond yields over time. While higher coupons can lift the opportunity cost of holding a non-yielding cryptocurrency, the historical record shows the relationship breaking down across cycles, including on 90-day correlation windows that often fail to produce a durable signal.
The latest spike took the U.S. 10-year to 5.13%, up 15 basis points in a single session, and lifted sovereign yields elsewhere. Under a textbook framework, that should be a headwind for BTC. In practice, bitcoin has frequently decoupled from rate moves, with episodes of both positive and negative short-term co-movements giving way to longer stretches of independence. That pattern undercuts the premise that bond markets set a reliable ceiling for the cryptocurrency’s performance.
Metric | Latest reading | Implication |
|---|
Bitcoin price | $83,262.77 | Held firm despite yield spike |
U.S. 10-year yield | 5.13% | Highest since 2007 |
Single-day change | +15 bps | Macro pressure in focus |
Correlation horizon | 90-day | Weak and inconsistent link |
Long-run pattern | Inconsistent | Limited predictive value |
Does the bond narrative still matter for crypto portfolios?
Only tactically, and even then with caution. The bond narrative can amplify short-term volatility as yields reset, but over most of bitcoin’s history it has lacked a stable, directional pull on BTC returns. That weak, inconsistent correlation reduces its usefulness as a strategic signal for cryptocurrency allocation.
Investors often frame bitcoin alongside other non-yielding assets, assuming rising coupons divert flows into fixed income. While that logic holds in traditional asset allocation models, bitcoin’s market structure, adoption cycles, and idiosyncratic liquidity dynamics have repeatedly overpowered rate-driven arguments. Episodes of macro sensitivity fade on a 90-day basis, leaving little lasting imprint on trend or market cap direction.
What should investors watch next?
Focus on whether yield moves persist long enough to affect liquidity conditions, not on a presumed one-for-one drag on BTC. Monitor the U.S. 10-year around 5.13% and subsequent basis-point shifts for signs of stress, but weigh them alongside crypto-native catalysts that historically overshadow bond market noise over multi-month periods.
In practice, the question is durability: a brief jump of 15 basis points can shake positioning, but the data suggest bitcoin’s longer-term path is rarely set by yield levels alone. With the 10-year at a 2007-era high, near-term cross-asset volatility is plausible, yet the historical pattern argues against treating bond yields as a reliable compass for bitcoin direction.
Bottom line: yields can move headlines, but bitcoin’s correlation with bonds has proven too unstable to anchor strategy. Portfolio decisions should account for the weak historical linkage and prioritize drivers that have shown more consistent explanatory power for BTC over time.