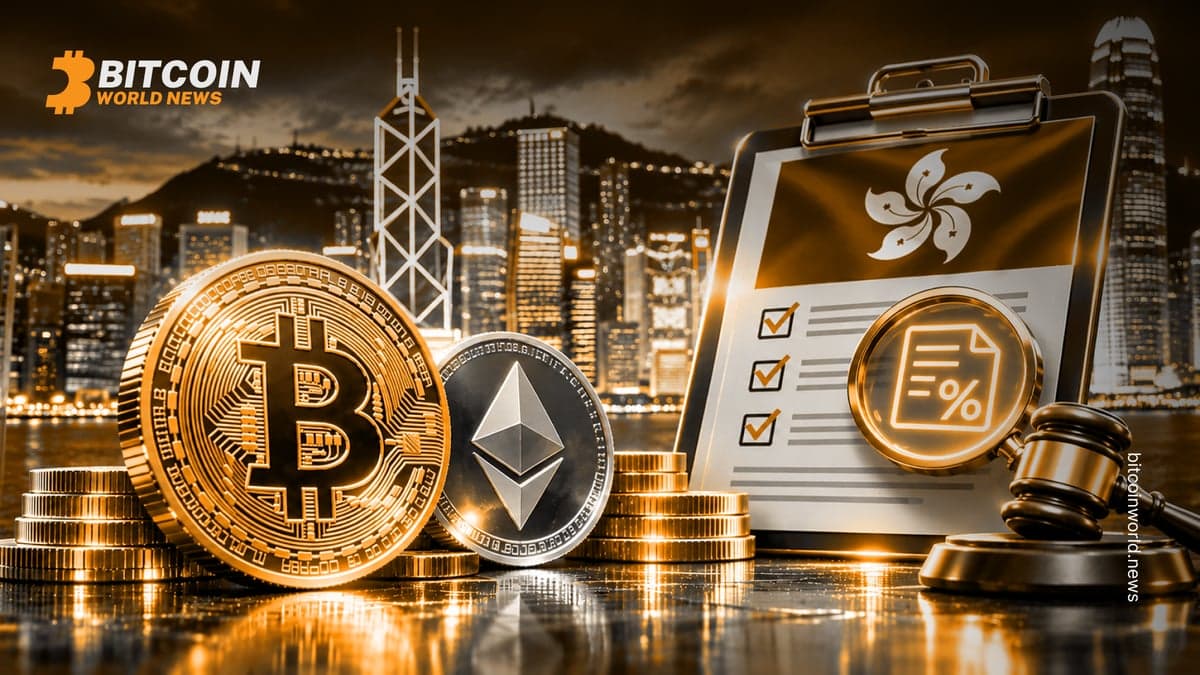
Hong Kong has passed a law that compels crypto exchanges to report customer transactions to tax authorities. The measure requires crypto firms to begin collecting customer and transaction data from 2027, with Hong Kong set to share that information with overseas tax authorities starting in 2028.
The framework places digital asset platforms under a clear tax-reporting mandate, aligning exchange operations with formal disclosure obligations. Firms operating in or serving the jurisdiction will need to build data collection, retention, and transfer processes in advance of the phased timeline.
What does the new Hong Kong crypto tax rule require?
Crypto exchanges must collect customer and transaction data, report it to domestic tax authorities, and prepare for cross-border information sharing. Collection obligations begin in 2027, while information exchanges with overseas tax authorities start in 2028. The measure formalizes how digital asset platforms capture and transmit activity data for tax administration.
By imposing standardized reporting, the law seeks to ensure tax authorities have visibility into cryptocurrency activity processed by exchanges. The requirement covers both identity and transaction details, elevating operational expectations for compliance, data governance, and secure transmission. Firms that serve Hong Kong clients will need to adapt onboarding and recordkeeping in advance of the 2027 collection start.
When do data collection and information sharing begin?
Crypto firms must begin collecting customer and transaction data in 2027. Cross-border information sharing by Hong Kong with overseas tax authorities starts in 2028, adding an international dimension to compliance planning. The staggered timeline gives exchanges time to build systems before cross-jurisdictional transfers commence.
The two-step schedule sets a clear order: first, establish comprehensive data capture and internal reporting; second, expand to structured sharing outside Hong Kong. Firms will need to align technology, vendor relationships, and internal controls to validate, store, and transmit required information accurately and on time as each milestone arrives.
With statutory obligations approaching, exchanges face an implementation runway focused on data mapping, documentation standards, and audit readiness ahead of the 2027 threshold. The subsequent shift in 2028 to overseas information sharing will require tested workflows for secure transmission and response protocols to meet foreign tax authority requests.
What should exchanges and customers prepare for next?
Exchanges should prioritize data architecture, customer due diligence updates, and reporting workflows to meet the 2027 collection start, followed by cross-border sharing in 2028. Customers can expect clearer disclosures and updated onboarding to align with the new requirements.
As the timeline advances, platforms will likely refine terms of service and consent mechanisms to reflect reporting obligations. Building robust records now may reduce friction as information sharing begins with overseas authorities in 2028, supporting smoother compliance across jurisdictions.
Hong Kong’s phased approach sets defined milestones. Execution over the next two years will determine how efficiently exchanges meet the new standards and how seamlessly cross-border data exchanges operate once they take effect.