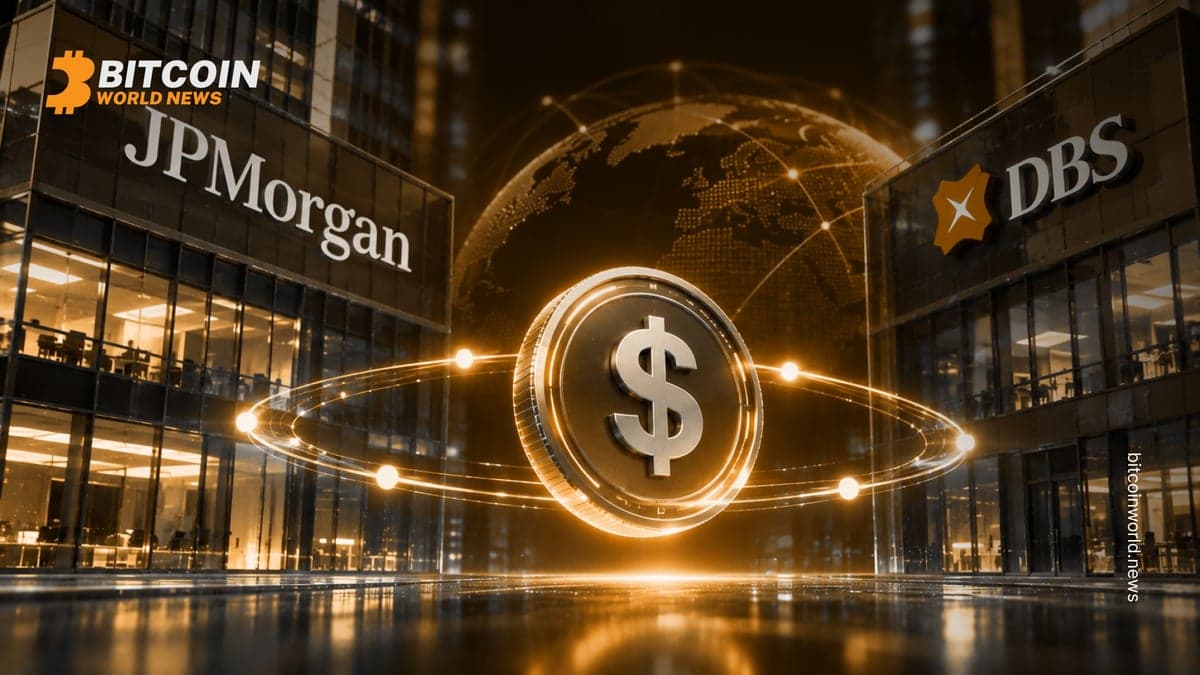
Tokenized U.S. dollars can now move between Singapore and the United States at any time, including weekends, after JPMorgan and DBS connected their blockchain-based deposit networks. The linkage allows approved clients to transfer funds cross-border on a 24/7 basis, extending settlement access beyond traditional weekday banking hours.
The banks’ connection brings always-on movement to tokenized dollar deposits across two major financial hubs. By enabling transfers outside standard cut-off times, the integration tests how bank-grade blockchain rails can streamline cross-border flows without waiting for Monday morning settlement windows.
What changed for cross-border dollar settlement?
Approved clients of JPMorgan and DBS can now move tokenized U.S. dollars between Singapore and the U.S. on a 24/7 basis, including weekends. The banks connected their blockchain-based deposit networks, turning what was a weekday-centric process into an always-on channel for permitted cross-border dollar transfers.
The operational shift centers on interoperability between the institutions’ tokenized deposit systems, not public cryptocurrencies. By linking private blockchain networks, the banks remove time-bound frictions—such as end-of-day and weekend pauses—that typically constrain international dollar movements. The capability is limited to approved participants, reflecting the permissioned design of bank-operated digital money platforms.
Institution | Asset Type | Jurisdictions | Availability |
|---|
JPMorgan | Tokenized U.S. dollar deposits | U.S. and Singapore | 24/7, including weekends |
DBS | Tokenized U.S. dollar deposits | Singapore and U.S. | 24/7, including weekends |
Why does weekend dollar movement matter?
Extending cross-border transfers to weekends reduces timing gaps and operational delays for clients seeking dollar liquidity outside weekday windows. The connected deposit networks demonstrate how tokenized money on permissioned blockchains can deliver continuous settlement, a key benefit long promised by distributed ledger technology in global payments.
For corporates and financial institutions operating across time zones, 24/7 access can compress funding cycles and mitigate cutoff risk. While participation remains restricted to approved clients, the live linkage between two large banks across two jurisdictions offers a tangible test of around-the-clock dollar mobility without waiting for traditional market reopen times.
What should institutions and clients watch next?
Adoption breadth and operational resilience will be the near-term markers to watch: how many approved clients use weekend transfers, how volumes evolve across Singapore–U.S. corridors, and how reliably the 24/7 rails perform under real workloads. Expansion to additional currencies, banks, or regions would signal a broader network effect for tokenized deposits.
Governance and standardization will also be pivotal. As more institutions interconnect permissioned systems, alignment on compliance, messaging, and settlement finality will determine how quickly always-on tokenized money can scale beyond a bilateral link. For now, the JPMorgan–DBS connection provides a concrete step toward continuous cross-border dollar movement.
If sustained, always-on tokenized deposit transfers could narrow the gap between instant domestic payments and slower cross-border flows, offering a bank-backed path to continuous settlement for dollar liquidity across major hubs.