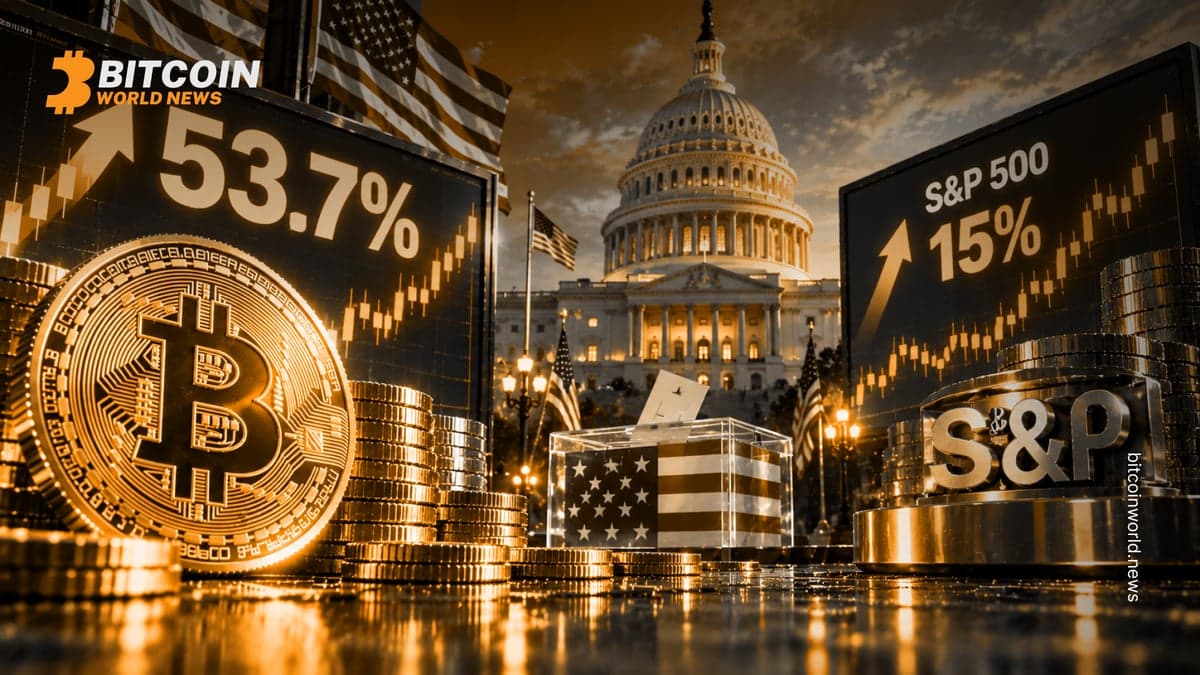
Bitcoin (BTC) has averaged a 53.7% gain in the 12 months following U.S. midterm elections, while the S&P 500 has risen 15% over the same post-election windows. The next midterm vote is set for Nov. 3. Since 2009, Bitcoin has seen four midterms; the analysis excludes 2010 due to the market’s tiny size at the time.
The return windows measure performance from the daily close on Election Day to the close on the same date a year later. Bitcoin last traded around $84,459.46. In the single excluded case — the 2010 midterm — Bitcoin surged 1,579% over the following year, but that outlier is considered unreliable given the market’s early, fringe state.
How strong has Bitcoin’s post‑midterm record been?
On average, Bitcoin rose 53.7% in the 12 months after Election Day across three observed midterm cycles since 2009, excluding 2010. Those gains are calculated from the daily close on Election Day to the same date a year later, underscoring a historically constructive pattern for the cryptocurrency after U.S. midterms.
Bitcoin has experienced four midterm election cycles since its inception in 2009. The analysis deliberately leaves out 2010, when liquidity and participation were minimal. In that year, BTC rallied 1,579% over the subsequent 12 months — a magnitude that highlights the distorting effect of early-stage market dynamics. By focusing on the three later cycles, the average offers a more representative snapshot of Bitcoin’s performance during a mature phase of the asset’s history.
Asset/Period | 12-month return | Notes |
|---|
Bitcoin (avg, post-midterms) | +53.7% | Average of three cycles since 2009, excludes 2010 |
S&P 500 (avg, post-midterms) | +15% | Measured over the same 12-month windows |
Bitcoin (2010 outlier) | +1,579% | Excluded as market was tiny and fringe |
How does Bitcoin’s record compare to the S&P 500?
Across the same 12-month post-midterm windows, the S&P 500 averaged a 15% gain, versus Bitcoin’s 53.7% average, excluding the 2010 outlier. That spread underscores Bitcoin’s historically higher volatility and return profile in the year following midterm elections.
Both sets of returns use the same methodology: measuring from the daily close on Election Day to the close on the same date a year later. The comparison spans the three post-2010 midterm cycles for Bitcoin and the corresponding equity-market windows, highlighting a consistent directional bias higher for risk assets over the period.
What should investors watch as Nov. 3 approaches?
History shows a positive skew for both Bitcoin and equities in the 12 months after U.S. midterms, with Bitcoin averaging 53.7% and the S&P 500 15%. Investors may track price behavior into and after Nov. 3, while recognizing that past performance — including the excluded 1,579% outlier in 2010 — does not guarantee future results.
With Bitcoin recently around $84,459.46, the upcoming election offers another test of the historical tendency identified across prior cycles since 2009. The post-election window will determine whether the pattern persists as market depth and participation remain far broader than in Bitcoin’s earliest years.
The next 12 months will reveal whether the established averages hold. For now, the historical record frames expectations: three post-midterm cycles with a 53.7% average gain for BTC and a 15% average for the S&P 500, measured on consistent, year-over-year close-to-close intervals.