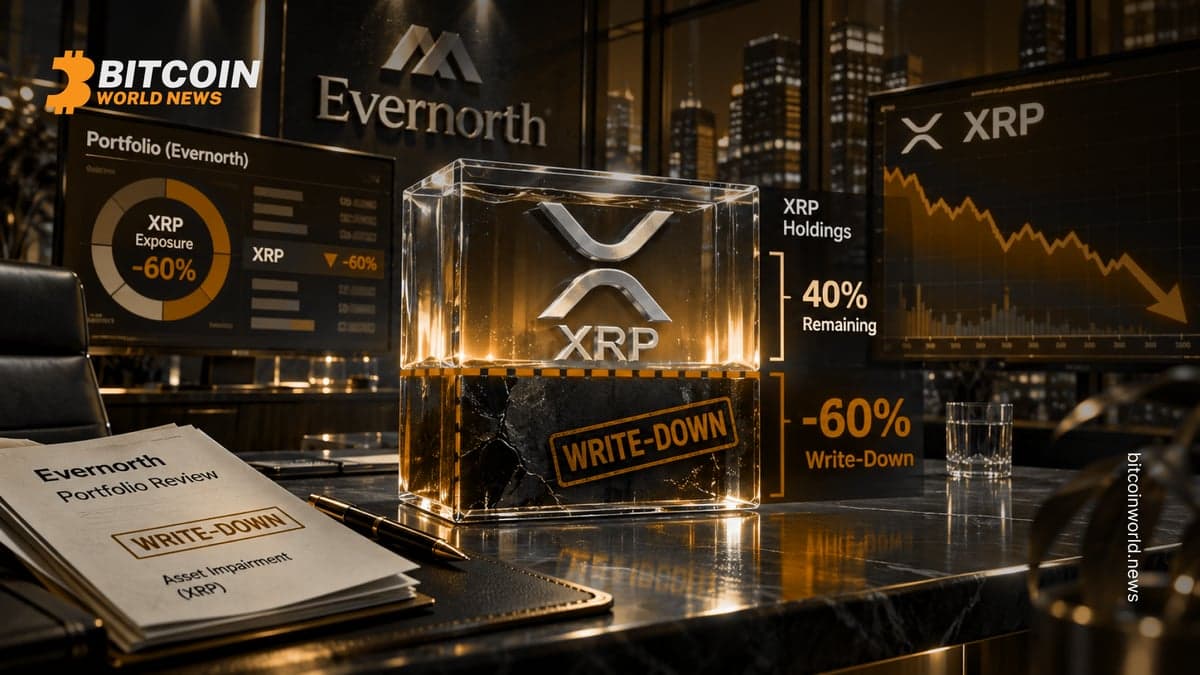
Ripple-backed Evernorth has written down its pre-listing XRP holdings by 60%, reflecting an accounting policy that recognizes price declines but does not reverse those impairments if XRP later recovers. The approach locks in downside without upward revisions, a notable stance for digital asset balance sheet management.
Ripple-backed Evernorth has written down its pre-listing XRP holdings by 60%, implementing an accounting approach that captures price declines but does not reverse impairments if XRP prices later recover. The policy choice has immediate balance sheet implications and sets a conservative bar for how crypto assets are carried over time.
The company’s treatment means historical volatility translates into recognized losses while any subsequent rebound in the cryptocurrency does not generate offsetting gains through impairment reversal. For stakeholders evaluating digital asset disclosures, such a framework can materially depress reported carrying values relative to market prices during recoveries.
What changed in Evernorth’s XRP accounting?
Evernorth recognized a 60% write-down on pre-listing XRP holdings and affirmed an accounting policy that records price declines but does not reverse those write-downs when XRP recovers. This effectively crystallizes impairments into carrying value and prioritizes downside recognition over subsequent appreciation on the balance sheet.
Sponsored
The decision highlights the tension in crypto accounting between fair-value sensitivity and impairment-driven conservatism. By locking in impairments without later upward adjustments, Evernorth’s reported asset values can trail market levels during rallies, shaping reported equity, leverage ratios, and performance metrics even when XRP prices improve after prior drawdowns.
Why does a no-reversal policy matter for XRP valuation?
Impairments that cannot be reversed can create a persistent gap between carrying value and market value when XRP rebounds. For readers assessing crypto exposure, the approach lowers reported asset bases in downturns and keeps them low in upturns, influencing comparability across issuers that use different policies.
This stance also affects period-to-period optics: losses are recognized promptly on declines, while recoveries are reflected only through future sales gains or alternative measurement events, not through impairment reversal. That asymmetry can dampen reported volatility at the expense of underreporting recoveries in carrying amounts.
What should investors watch next?
Focus on how Evernorth’s carrying values evolve relative to prevailing XRP prices and whether future disclosures clarify the triggers, cadence, or scope of impairment testing. Monitoring these details will help gauge the ongoing impact of the no-reversal policy on reported results and asset coverage metrics.
Comparisons to peers’ crypto accounting choices may further contextualize Evernorth’s stance. While market prices will continue to move, the policy framework will determine how quickly, and to what extent, those moves are reflected in reported figures for XRP holdings.
Bottom line: a 60% write-down paired with a prohibition on reversing impairments sets a conservative precedent for digital asset accounting, with implications for transparency, comparability, and the interpretation of reported capital strength when market conditions change.
This article is for informational purposes only and does not constitute financial, investment, or trading advice. Cryptocurrency markets are highly volatile and carry significant risk. Always conduct your own research (DYOR) and consult a qualified financial advisor before making investment decisions. Past performance does not guarantee future results.
Share
The crypto brief, in your inbox
BTC, markets, and the stories that moved crypto — daily, no noise.